- Home
- Credit Score
- Experian Credit Score
Experian Credit Information Report
A credit report is a detailed record of how you’ve handled borrowing and repaying money. Companies like Experian collect this information and use it to create your Experian Credit Report, which can affect your ability to borrow money, get a job, or rent a home. Here’s what you need to know about Experian and the importance of an Experian Credit Report.
Experian is one of the leading credit reporting agencies. It gathers and maintains information about your financial behaviour, including your history of paying debts, the amount of credit you have available, how much of your available credit you use, and whether you make payments on time. They compile this information into a Credit Information Report (CIR), which is crucial to your Experian Credit Score.
Your Experian Credit Information Report influences your Experian Credit Score, a number between 300 and 850 representing your creditworthiness or how likely you are to repay borrowed money. A higher Experian Credit Score can make getting loans and credit cards easier and cheaper.

- Instant Results
- No Hidden Fees
- Secure & Confidential
- No Impact on Your Credit Report
I agree to the Terms and Conditions of TUCIBIL and hereby provide explicit consent to share my Credit Information with Urban Money Private Limited.
Verify your number
Enter 6 Digit OTP
Change mobile number
Table of Content
Understanding Your Experian Credit Score
Your Experian Credit Score is a key indicator of your financial health. It reflects how reliably you’ve managed credit and payments in the past. The higher your score, the more likely lenders will see you as a low-risk borrower, which can lead to better interest rates and more favourable loan terms.
Here’s a simple table to help you interpret your score:
| Score Range | Category | Likely Impact |
| 300-579 | Poor | May have difficulty securing credit; higher interest rates are likely |
| 580-669 | Fair | Considered subprime; might obtain credit but with higher rates |
| 670-739 | Good | Viewed as an average borrower; reasonable rates |
| 740-799 | Very Good | Likely to receive better than average rates |
| 800-850 | Excellent | Eligible for the best rates and favourable terms |
Your Experian Credit Score is calculated based on several factors in your credit report, as outlined in the table below:
| Factor | Influence | Description |
| Payment History | 35% | Tracks timeliness of past payments |
| Amounts Owed | 30% | Total credit used vs. credit available |
| Length of Credit History | 15% | A longer credit history boosts the score |
| Credit Mix | 10% | A variety of credit types helps the score |
| New Credit | 10% | Opening multiple new accounts may lower the score |
What Information is in Your Experian Credit Report?
Your Experian Credit Report is a comprehensive document containing several information types, all of which help lenders and other financial institutions assess your creditworthiness. Here’s what you can expect to find in your report:
Personal Information
- Name, address, and Social Security number: These identify you and ensure that all financial data is accurately linked to your report.
- Employment information: This helps lenders understand your employment stability.
Credit Accounts (Trade Lines)
- Type of account (credit card, mortgage, auto loan, etc.): Different accounts can affect your score differently.
- Date the account was opened: Older accounts can improve your score.
- Credit limit or loan amount: This shows the total amount of credit granted.
- Account balance: How much do you currently owe?
- Payment history: Includes late payments, defaults, and regular, on-time payments.
Credit Inquiries
- Hard inquiries: These occur when a lender checks your credit to grant you credit. Too many hard inquiries can lower your score.
- Soft inquiries: This happens when you check your own credit or when a lender pre-approves you for an offer. These do not affect your score.
Public Records and Collections
- Bankruptcies, foreclosures, liens, and civil judgments: Such events can significantly negatively impact your credit score.
- Accounts in collections: These are debts sold to a collection agency after non-payment.
Consumer Statements
- Dispute statements: If you have disputed an item in your report, this statement can explain your side of the story.
What is Experian?
Experian is a global information services company that started in the United States in the 1960s as TRW Information Systems. It evolved over the decades, undergoing several changes, including a name change to Experian in the 1990s after being acquired by GUS plc, a British company. Today, Experian is one of the largest credit reporting agencies in the world, providing data and analytical tools to clients globally. The company’s headquarters are in Dublin, Ireland, with operational offices across North America, Latin America, the UK, and the Asia-Pacific region.
What Does Experian Do, and How Does it Help You?
1. Collects and Shares Credit Information
Experian plays a crucial role in the financial ecosystem by collecting detailed credit and financial information from various sources like banks, credit card companies, and public records. This information is compiled into individual credit reports that reflect a person’s credit history, including their reliability in paying off debts. These reports are used by lenders, such as banks and credit card companies, to determine whether to grant loans or credit.
2. Helps Lenders Make Decisions
Lenders rely on credit reports from Experian to make informed decisions quickly. These reports help lenders assess the risk of lending to individuals, influencing the terms of loans or credit limits offered. Experian facilitates a fair and efficient lending process by providing a clear picture of credit history.
3. Protects Against Fraud
Experian helps protect individuals from identity theft and financial fraud. The company offers monitoring services that alert consumers to potentially fraudulent activity involving their personal information. This proactive approach helps prevent financial losses and safeguards consumer credit.
4. Educates Consumers
Experian is committed to financial education, helping individuals understand their credit and how to manage it effectively. By providing access to credit scores, reports, and explanatory resources, Experian empowers consumers to take control of their financial health. They offer tips on improving credit scores and managing debt, which are essential for financial stability.
5. Manages Credit Disputes
If there are errors in a credit report, Experian provides a mechanism for consumers to dispute inaccuracies. Correcting these errors can help improve a person’s credit score, enhancing their ability to borrow under favorable conditions.
What Affects Your Experian Credit Score?
Understanding what factors influence your Experian Credit Score is crucial if you want to improve or maintain your credit health. Your credit score is a number that lenders use to decide how likely you are to repay a loan. A higher score means you are at a lower risk, which can lead to better interest rates and loan terms. Here are the key factors that affect your Experian Credit Score:
Payment History (35% of your score)
- Timeliness of Payments: Your payment history is the most significant part of your score. This includes records of whether you pay your bills on time. Late payments, defaults, and bankruptcies hurt your score.
- Severity and Frequency: The more recent, frequent, and severe the lateness, the greater the impact on your score.
Credit Utilisation (30% of your score)
- Amount Owed vs. Credit Limit: This measures how much of your available credit you use. Using a high percentage of your credit limit can indicate that you are overextended and may pose a risk to lenders.
- Keeping Balances Low: To positively affect your score, it’s generally recommended that you keep your credit utilization below 30% of your total credit limit.
Length of Credit History (15% of your score)
- Age of Accounts: A longer credit history tends to impact your score positively. It shows you have experience managing credit.
- Average Age of Accounts: Older credit accounts are beneficial because they demonstrate a long history of responsibly managing credit.
Types of Credit in Use (10% of your score)
- Credit Mix: Lenders like to see various credit types, including credit cards, retail accounts, installment loans, finance company accounts, and mortgage loans.
- Diversity of Accounts: A mix of different types of credit can positively impact your score, showing you can handle different types of lending responsibly.
New Credit (10% of your score)
- Recent Credit Inquiries: Each time you apply for a new credit, your credit score can drop slightly, temporarily. Frequent applications can be seen as a higher risk.
- Newly Opened Accounts: Opening several new accounts quickly can be risky, especially if you don’t have a long credit history.
Other Factors
- Public Records: Bankruptcies, foreclosures, and court judgments such as liens can significantly damage your credit score.
- Debt Settlements: Settling accounts for less than the original amount owed can negatively affect your credit score, although not as severely as a bankruptcy.
Why Your Experian Report and Score Matter?
Your Experian Credit Report and Credit Score are essential in several facets of your personal and financial life. Recognising their significance can guide you to smarter financial choices and motivate you to enhance your overall financial health. Here’s why they are so important:
Credit Opportunities
A solid Experian Credit Score opens doors to various credit options. Lenders examine your score to determine your creditworthiness when you apply for loans or credit cards. Higher scores usually mean better approval odds and favorable terms, including lower interest rates.
Housing Options
When you want to rent a home, your credit score could be a deciding factor. Landlords often use credit scores to judge whether a prospective tenant will pay rent reliably. A favorable score can smooth the path to securing your preferred residence.
Job Prospects
Employers might review your credit report in job sectors involving financial management or handling sensitive information. A positive report can reflect well on you, showing potential employers you are responsible and trustworthy.
Insurance Rates
Your credit score may influence what you pay for auto or home insurance. Insurers sometimes use credit scores to determine premiums, with higher scores frequently leading to lower costs.
Understanding Financial Health
Monitoring your Experian Credit Report and Score is crucial for maintaining a healthy financial status. It helps you gauge your financial well-being, pinpoint areas for improvement, and detect any inaccuracies or fraudulent activities that could impact your financial access.
Negotiation Leverage
With a high credit score, you can negotiate terms on loans and credit limits. Financial institutions see you as a lower risk, which can translate into better financial deals.
Saving Money
In the long run, a higher credit score can save you money. It can lead to lower interest payments on loans and credit cards, reducing the total amount you spend on debt repayments.
Services Experian Offers
Experian offers comprehensive services to individuals and businesses, enhancing their ability to manage credit, prevent fraud, and make informed decisions. Below is a table that outlines the key services provided by Experian:
| Service Category | Description |
| Credit Reporting | Experian collects and maintains credit reports for individuals, detailing credit history, card usage, loan history, and payment records. These reports are essential for calculating credit scores, which are used in various financial decisions. |
| Credit Monitoring and Alerts | This service provides real-time alerts on changes to your credit report, such as new inquiries or accounts, helping to detect and minimize the impact of identity theft. |
| Identity Theft Protection | Includes services like identity theft insurance, fraud resolution assistance, and lost wallet protection to safeguard personal information and assist in recovery if compromised. |
| Business Services | Experian offers businesses credit risk management, fraud prevention, and customer relationship improvement tools, including business credit reports and analytics for predicting customer behavior. |
| Decision Analytics | Utilizing advanced analytics, Experian helps businesses analyze consumer data to make informed decisions, tailor products, manage risks, and increase profitability. |
| Automotive Information Services | Provides detailed reports on automotive credit, market trends, and vehicle history, benefiting dealers, manufacturers, and buyers in the automotive industry. |
| Consumer Services | Tools and resources for consumers to check credit scores, find credit offers, and improve credit management strategies, along with educational resources about credit health. |
| Dispute Services | Facilitates disputing inaccuracies on credit reports, allowing individuals to correct erroneous information to maintain an accurate and fair credit record. |
How to Get Your Experian Report and Score Online?
Obtaining your Experian credit report and score online is straightforward. Here are the steps you can follow to access your credit information quickly and without a fee:
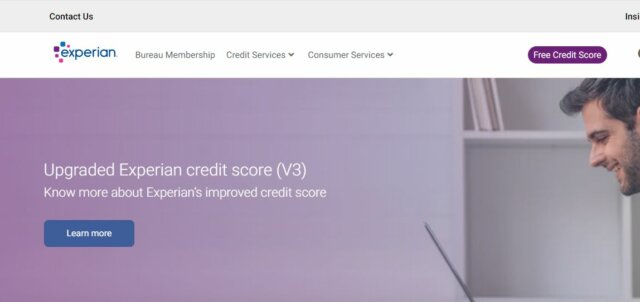
- Visit Experian’s Official Website: Start by navigating to the official Experian website. Make sure you are visiting the correct site to ensure your personal information is secure.
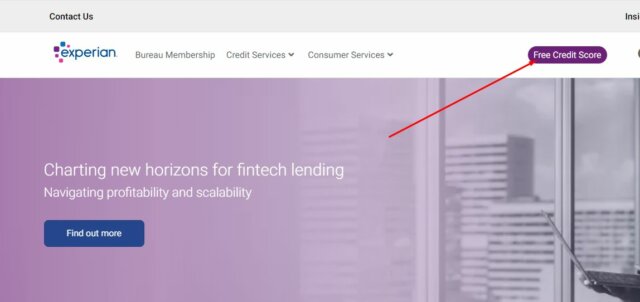
- Find the Credit Report Section: Once you are on the Experian website, look for the option to check your free credit report and FICO® Score. This is typically easy to find from the homepage or under a marked section like “Credit Report” or “Free Credit Score.”
- Provide Personal Information: To view your credit report and score, you must provide some basic personal information. This may include your full name, address, Social Security number, and date of birth. Ensure you enter this information accurately to proceed smoothly to the next step.
- Verify Your Identity: Experian takes security seriously and will require you to verify your identity. This may involve answering personal questions based on your credit history or verifying your identity through Time Password (OTP) authentication sent to your phone or email. Follow the prompts to complete this verification process.
- Access Your Credit Report and Score: After verifying your identity, you can access your Experian credit report and FICO® Score. There is no need for a credit card to view this information online. You can review your credit status, check for inaccuracies, and understand your credit health.
How to Get Your Experian Report and Score Without Using the Internet
To obtain your Experian credit report and score without using the Internet, you can follow these steps:
- Call Experian: You can request your credit report by calling Experian at 888-EXPERIAN (888-397-3742).
- Request by Mail: If you prefer, you can also send your request in writing to Experian’s postal address. You must include proof of your identity, such as a copy of your driver’s licence and a utility bill or bank statement for address verification.
- Annual Credit Report: You can request a free copy of your credit report from each of the three credit reporting companies at AnnualCreditReport.com once every 12 months. However, this will require you to enter a Social Security number.
How to Fix Mistakes in Your Experian Report Online
If you need to fix mistakes in your Experian credit report online, here’s a step-by-step guide to help you through the process:
- Access the Dispute Center: Visit Experian’s online Dispute Center to start the dispute process.
- Identify Errors: Review your credit report carefully and identify any inaccuracies or errors.
- Initiate a Dispute: For each error, indicate the reason for your dispute. You can do this by selecting the appropriate reason from a dropdown box provided.
- Submit Documentation: Upload any relevant documents confirming the information you’re disputing inaccurately.
- Review and Submit: Before hitting submit, review your dispute request to ensure all details are correct and complete.
- Follow-Up: After you submit your dispute, Experian will investigate the issue. If necessary, they will coordinate with the relevant financial institution, and you will be notified of the outcome via email.
How Experian Figures Out Your Credit Score
Experian calculates your credit score based on a model that considers various aspects of your financial behaviour. Key factors include your payment history, which accounts for 35% of your score and reflects whether you’ve made your payments on time; your credit utilisation, which contributes 30% and examines how much of your available credit you’re using; the length of your credit history, making up 15%, highlighting the age of your accounts and how long you’ve been managing credit; the types of credit in use, accounting for 10%, where having a mix of credit types (like credit cards, loans, and mortgages) shows your ability to handle diverse financial responsibilities; and finally, new credit inquiries, also at 10%, where recent credit applications can temporarily lower your score. These elements help Experian provide lenders with a numerical representation of your creditworthiness.
Tips to Make Your Experian Credit Score Better
Improving your Experian Credit Score is an important step towards achieving financial stability and unlocking new opportunities. By following these simple tips, you can enhance your credit score and, consequently, your ability to secure better financial terms. Here’s how you can effectively improve your score:
- Pay Bills on Time: Consistently paying your bills on time is crucial. Late payments can significantly damage your credit score. Consider setting up automatic payments or reminders to ensure you never miss a due date.
- Keep Credit Utilisation Low: Aim to use less than 30% of your available credit. Lenders may consider high credit utilisation a sign of financial distress and risk.
- Regularly Check Your Credit Report: Access your Experian Credit Report regularly to ensure no inaccuracies or fraudulent activities. If you spot errors, report them immediately to Experian for correction.
- Limit New Credit Applications: Each time you apply for credit, your credit score can dip slightly. Apply for new credit sparingly and only as needed to minimise this impact.
- Maintain a Diverse Credit Mix: A mix of credit types, such as credit cards, personal loans, and a mortgage, can positively affect your score. It shows that you can manage different types of credit responsibly.
- Keep Old Accounts Open: The length of your credit history matters. Keeping older credit accounts open—even if you’re not using them—can help lengthen your credit history and potentially boost your score.

 Written By

 Reviewed By
Last Updated: 8th September 2026
Latest from the Credit Score Blog
Get in-depth knowledge about all things related to Credit Score and your finances
Trade Credit
Trade credit meaning Trade credit is credit extended by one business to another, allowing the buyer to purchase goods or services and pay later. In simple terms, the supplier becomes the creditor, and the buyer becomes t
How to Get 900 CIBIL Score
Is 900 the maximum CIBIL score? Yes, 900 is the maximum CIBIL score on the scale set by TransUnion CIBIL. The scoring model runs strictly between 300 and 900. A 300 rating shows high default risk, while 900 reflects a cl
Methods of Credit Control by RBI
What is credit control and why does the RBI use it In the Indian banking system, credit control refers to measures that influence the volume, cost, and availability of loans and advances. The Reserve Bank of India uses m
Grameen Credit Score
What is the Grameen Credit Score? The Grameen Credit Score is designed to provide a more suitable way of evaluating the creditworthiness of people in rural areas. In simple terms, the Grameen credit score is a credit ass
Does Foreclosure Affect CIBIL Score
What is loan foreclosure? Personal loan foreclosure means repaying the entire outstanding loan before the scheduled tenure ends. The borrower pays the remaining principal, applicable interest and any permitted charges. T
Four Types of Credit
What is credit? A quick recap Credit refers to money borrowed from a lender or goods and services received from a provider with an agreement to pay later. Unlike using your own money, taking out a loan creates a repaymen
Guarantor's Bad CIBIL Score Affect the Primary Borrower
Does the Guarantor’s Credit Score Matter? The guarantor’s CIBIL score matters very significantly. Lenders assess the CIBIL reports of the guarantor and borrower before approving loan amounts. Managing joint accounts and
Does Being a Guarantor Affect Your CIBIL Score?
What Is a Loan Guarantor? A loan guarantor is a person who takes all financial responsibilities for the primary borrower. If the primary borrower misses a payment, the guarantor takes responsibility. Lenders primarily ev
Does having multiple credit cards affect CIBIL score?
It depends on how you manage them Holding several credit cards can boost your rating just as easily as it can drag it down. If you pay every bill on time and keep your balances low across all accounts, having extra cards
Does prepaying or foreclosing a loan early lower your score?
What is loan prepayment? Loan prepayment occurs when you pay a lump sum toward your principal balance before the scheduled EMI due date, while keeping the overall loan active. You can make partial prepayments to reduce y
Do credit limit increase requests affect your CIBIL score?
What is a credit limit increase? A credit limit increase, also known as a credit limit enhancement, raises the maximum amount of money your bank allows you to spend on a credit card. If your card currently carries a limi
Does closing an old credit card hurt your CIBIL score?
How credit history length affects CIBIL score Length of credit history contributes roughly 15% to your overall CIBIL score calculation. Credit scoring models favor stability. A long, uninterrupted paper trail proves to b
Duplicate Loan Account in CIBIL Report
What is a duplicate loan account entry in CIBIL? A duplicate loan entry in CIBIL refers to two or more account records that actually represent the same loan. For example, a borrower may have one personal loan from a bank
Credit Score vs Credit Utilisation Ratio
What is a credit score? A credit score is a three-digit numerical summary ranging from 300 to 900 that represents your creditworthiness to lenders. Indian credit bureaus: TransUnion CIBIL, Experian, Equifax, and CRIF Hig
CIBIL Score vs CIBIL Rank Difference
CIBIL score A CIBIL Score is a three-digit summary of an individual’s credit history. It ranges from 300 to 900, with a score closer to 900 generally indicating a stronger credit profile. The CIBIL score calculation is b

